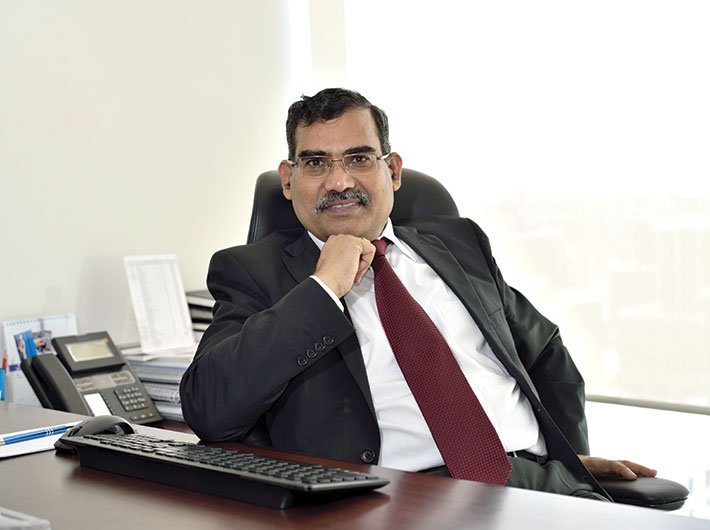
In April, former Reserve Bank of India (RBI) governor Raghuram Rajan launched united payment interface (UPI), a payment technology product by National Payments Corporation of India (NPCI), an umbrella organisation for all retail payment system in the country. UPI is a mobile interface that has a unique ‘push and pull’ feature for receiving and making payments using smartphones, through different m-banking applications, which are UPI compliant. It also allows customers to hide their bank details by a financial address that can be an Aadhaar number, mobile number or a virtual ID. Moreover, a customer can access his/her multiple bank accounts on a single application. In conversation with Taru Bhatia, Hota explains how UPI will contribute to the cashless economy.
What role does UPI play in the ‘less-cash movement’ in India?
UPI is primarily a mobile first payment technology. The country has 250 million smartphone users and the number is growing at the rate of about 25 million per year. The ecosystem for development of software is also growing fast. So, with the UPI system being completely interoperable, simpler than erstwhile IMPS [immediate payment service] system and easily available on affordable smartphones in the hands of many, it can serve as a critical component for cashless initiatives of the country. It is a smartphone-layered technology. Smartphones are growing, applications development atmosphere is growing, then a greater degree of acceptance of mobile as a channel is growing, and that is why it is important in less-cash economy.
Is UPI technology limited to only smartphone users and therefore to the urban India?
It is limited to smartphone [users] but not to urban society, because smartphones are available at about Rs 2,000. Access to data is also widely available and not limited to only urban regions. So, UPI can be used everywhere; [one] only needs a smartphone.
How UPI is different from IMPS?
IMPS is a system for 24x7 money transfer. UPI is a subset for IMPS as of now. Later on if UPI grows phenomenally and once all major banks start using UPI instead of IMPS then we can think of other services which can be done only on UPI. Other services include receiving and payment of money, balance enquiry, Aadhaar query and bill payments. We cannot add these in IMPS but in UPI.
What is the role of Aadhaar in UPI?
We are planning to make Aadhaar authentication a part of the UPI. Instead of PIN, fingerprint and iris scan can be done for KYC. As of now, a fingerprint-based device of Aadhaar standard is not available, but ‘iris phones’ of Aadhaar standards are available.
But aren’t those phones expensive and out of reach of common users?
Expensive phones at present would be useful for biometrics authentication. Ordinary smartphones users can still use PIN for authentication. UPI will not rely on authentication with only Aadhaar. Multiple options will be available to users.
What is the roadmap to expand UPI platform to non-banking players?
Till March 2017, our focus is only on banks. To include non-banking players, we need RBI’s approval. And I suppose, RBI at present wants us to roll out UPI with banks first. After March, we will see a lot of payment banks and the non-banks who are currently asking for UPI compliance would have already become the payment banks like Paytm. Then we will evaluate the situation. Currently, 21 banks are onboard while testing for 14 banks is in progress.
Will UPI revolutionise e-commerce space in India?
One of the most important things is making use of UPI on e-commerce platform. So the collection of payment would be pretty easier than card payments.
What could be possible challenges for the UPI?
One challenge that I see is that in IMPS there are 85 banks over the period of last three years. To get that number on UPI platform with wide acceptability in a very compressed time is difficult. Second challenge is customer adoption. We have to do substantial amount of work for this because only a good technology will not help; we have to do a lot of awareness campaigns. Otherwise, implementation challenge will always be there since banks are coming up with a wide variety of services and we cannot demand focused attention from top executives of banks only for UPI. It is an issue based on their criticality of attention but this is quite a complex payment mechanism and requires time and attention from senior management of banks.
(The interview appears in the October 16-31, 2016 issue)