Speed does not matter if you are travelling in the wrong direction. North Block mandarins should have realised that when Indian economy was registering higher growth rates
It was not so long ago that many people were very upbeat about the prospects of the Indian economy. This sentiment was induced by the maintenance of exceptionally high rates of aggregate economic growth since 2003-04, and the fact that the initial effects of the global crisis on Indian growth were not that dramatic and apparently short-lived. The mood, however, is very different now.
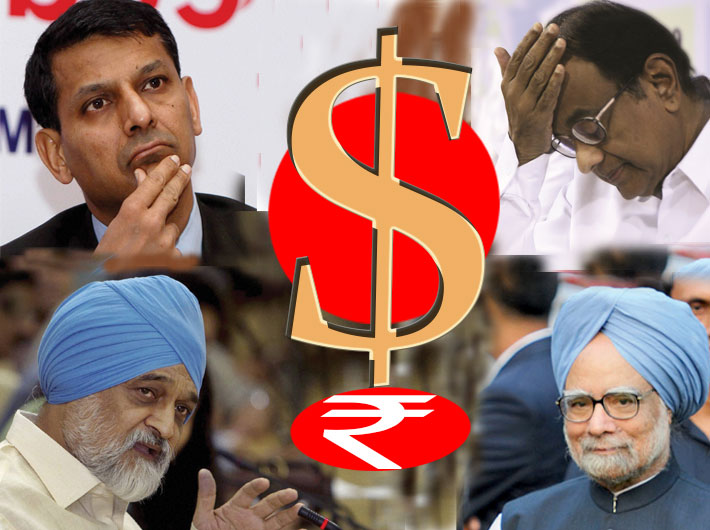
GDP growth has slowed down considerably even as inflation levels remain high. A large current account deficit combined with the drying up of foreign capital flows has led to a slide in the value of the Indian rupee. India has also been downgraded by international rating agencies with worse being threatened. There is much talk about the need to end the ‘policy paralysis’ and pushing the reform agenda to put the economy back on track.
The problem, however, is that this discourse does not recognise a fundamental truth about the current difficulties of the Indian economy. India’s economic woes are not the result of the economy going off some trajectory it was earlier on. They are the outcomes of that very trajectory.
If one looks closely at the evidence, it would be clear that India’s economic crisis is neither temporary nor a recent development. The beginnings of the agrarian crisis, afflicting the sector in which more than half the workforce is still employed, dates back to the mid-1990s at least. One of its eventual consequences was the growth of food prices at a fast clip, a phenomenon that has been around for the last six years or so.
Industrial growth has also been unsteady over the last two decades, having already experienced a six-year slowdown in the late 1990s to early 2000s – it is services and construction that have maintained Indian growth and contributed most of it. The growth of private corporate investment, a large chunk of which tends to be in the manufacturing sector, collapsed then; just as it has now. India’s trade deficit had been rapidly widening since the early years of this century much before the global crisis erupted. Indian foreign exchange reserves during this period were built up on the basis of foreign capital inflows dominated by short-term financial flows, which by their very nature are volatile.
Most importantly, even in the period of high GDP growth, employment growth was very meagre in the segments of the economy in which this growth was concentrated and income growth of many employees even less. In the organised industrial sector, for example, the average levels of real wages per worker were lower when the economy was growing at nearly 9 percent per annum than they were in the early 1990s. Nearly 90 percent of the workforce on the other hand is reliant on work in the informal sector. An employment and incomes crisis has thus afflicted large sections of the Indian population for the last two decades. An indicator of this is that per capita consumption of basic food items (food grains, fruits and vegetables taken together) has generally been lower in this period than it was at the beginning of the 1990s.
It is the narrow spread of Indian growth that lies behind its instability, particularly in the industrial sector, and also that of investment. This narrowness has prevented the development of a broad-based expansion of demand for manufactured products. Those who would spend rising incomes increasingly on manufactured consumer goods have not experienced such income growth, while at the upper end of the income ladder increasing incomes led to increased diversification of demand with an increasing proportion going towards services.
In such circumstances it is not consumption growth but investment, and specifically private corporate investment, which has become the principal expenditure influencing industrial growth. However, the essential difficulty in sustaining private corporate investment is that while much of this investment tends to go into manufacturing, a disproportionate share of the growth in output comes from services. Manufacturing investment creates demand for industrial products but it simultaneously increases the capacity for producing these products. An excessive dependence of industrial demand on manufacturing investment unsupported by adequate consumption growth creates the tendency for capacity creation in manufacturing to outpace demand growth.
That India has not been very competitive in a sufficiently large range of manufactured products to grow on the basis of an export surplus further aggravates its difficulties. Any investment boom therefore becomes prone to collapse. This is precisely what happened in the late 1990s, and the same is being repeated now in a context where the dependence on investment expenditure to sustain demand has increased further.
The fact that there are dimensions of the crisis that predate the current slowdown does not, however, mean that there is nothing new in the current context that is important. As long as the fundamental trajectory does not change, the effects of high growth and a slowdown on the employment and incomes crisis are not symmetrical. While high growth may not translate into rapid rise in employment and incomes for the majority, a slowdown will certainly produce an adverse effect on these.
Much of the 8 to 9 percent growth reflected ‘productivity’ increases and the corresponding increase in employment was barely keeping pace with the growth of the workforce. Even if productivity growth weakens, a slowdown of GDP growth to the 5 to 5.5 percent range could very well mean not just a jobless growth but even a contraction in employment. If inflation remains high in such a background, especially with high food price inflation as its major component, the levels of economic distress for a large number of citizens may reach intolerable levels.
On top of this is the worrisome external sector situation aggravated by the global economic situation – India’s record of avoiding a foreign currency crisis could be brought to a swift end which would bring in its wake the severe economic pain that so many countries have experienced.
Clearly, therefore, there is much to worry about the current state of the Indian economy. Something, therefore, does need to be done about it, but this requires a mindset change in Indian policymaking. Instead of relying on integration with the global economy, the domestic market has to be the basis for growth. For this market to be converted from merely a potential to an actual market, growth has to be of a kind whose benefits are widely spread. Such a growth cannot be realised by relying on the private corporate sector to drive growth and inducing it to play this role by numerous tax concessions and other ‘reforms’. Rather, increased resource mobilisation and expansion of public investment and expenditure in a number of neglected areas like agriculture, infrastructure and the social sector (health, education etc) are necessary.
The unfortunate reality, however, is that powerful corporate and financial interests appear likely to be able to use the current crisis to extract precisely what is not desirable – namely, further corporate-friendly ‘reforms’.