A global economic crash is unlikely, but a painful, extended slowdown is becoming increasingly unavoidable
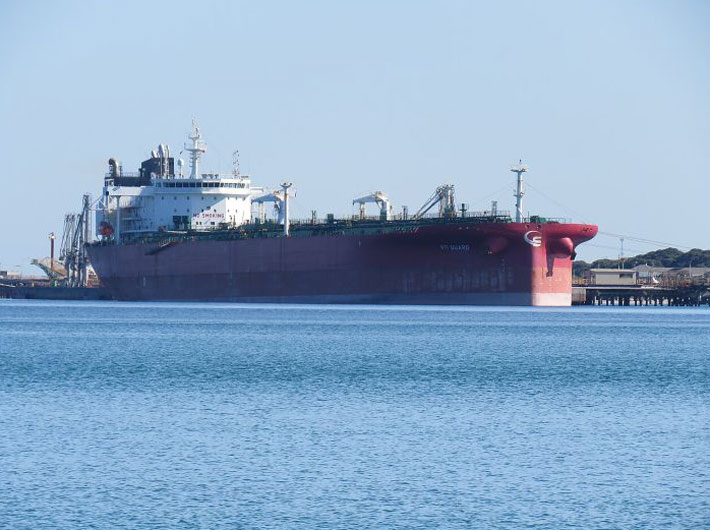
As tensions rise between Iran and Israel, the potential for ongoing disruption in the Strait of Hormuz has driven global energy markets very unstable. With crude prices climbing towards $140 per barrel, the world is facing its most significant oil shock since 1973.
However, the response to the headline question is more complex than alarmist views imply. A global economic crash is unlikely, but a painful, extended slowdown is becoming increasingly unavoidable.
Why a Full-Blown Crash Is Unlikely
In contrast to earlier crises, the current global economy is not fully vulnerable. Several structural safeguards reduce the likelihood of a complete collapse.
Firstly, oil supply is much more diversified. Unlike the 1970s, when OPEC controlled over 80% of the market, nearly 40% of today's supply comes from outside the Middle East, including US shale, Brazil, and Canada. Even partial diversion from Gulf producers and emergency releases by the International Energy Agency provide short-term relief.
Secondly, central banks possess considerable resources. The Federal Reserve and European Central Bank have shown their readiness to provide liquidity on a large scale. If economic growth declines significantly, monetary easing can be implemented swiftly to prevent systemic failure.
Thirdly, corporate risk management has advanced. A significant portion of global oil consumption is pre-hedged, which delays the immediate impact of price shocks on balance sheets.
Lastly, the global economy's structure has changed. Nearly 40% of global GDP now comes from relatively low-energy sectors like digital services, finance, and pharmaceuticals. Economies are no longer as dependent on oil as they once were.
In summary, these buffers suggest that a conventional "crash" of the global economy is improbable.
The Real Risk: A Global Stagnation Trap
While a collapse appears improbable, stagnation is still a significant risk. Oil shocks impact the economy through multiple interconnected pathways, each aggravating the others. Rising fuel prices increase transportation and production expenses, which subsequently lead to inflation. Shipping disruptions raise trade costs, while financial markets react with instability and capital flight. The result is a stagflationary situation, characterized by slowing growth alongside persistent inflation.
The International Monetary Fund forecasts a global growth rate of 3.1% for 2026; however, this figure could realistically decline to approximately 2%, leading to output losses between $2 and $2.5 trillion. Inflation is expected to rise by 1 to 2% globally, which may force central banks to delay interest rate cuts despite a slowdown in growth.
This illustrates the real danger: not a sudden downfall, but a slow decline that diminishes incomes, investment, and economic confidence gradually over time.
Uneven Global Impact
The effects of this slowdown will not be distributed evenly. Advanced economies with varied energy sources may weather the shock better. For instance, the United States gains advantages from its domestic shale production, which reduces its vulnerability.
Conversely, energy importing nations, particularly in Asia, will face significantly more severe consequences. Countries like India, Japan, and South Korea are likely to deal with expanding trade deficits, currency pressures, and rising inflation. Europe, which is still recovering from earlier gas supply interruptions, faces further vulnerabilities, raising the chances of near-stagnation.
India’s High-Stakes Exposure
With almost 90% of its crude oil coming from imports, any price increases swiftly affect the domestic economy. Increasing transportation expenses drive up food prices, hitting lower-income families the hardest. Governments face growing subsidy demands, limiting their ability to allocate funds to other critical areas. Key sectors like healthcare are also under significant strain.
A prolonged rise could increase inflation up to 7–8%, and expand the current account deficit to approximately 2.5% of GDP according to estimates derived from RBI and IMF. Higher oil prices also exert pressure on the rupee and limit fiscal flexibility, as the government is often forced to balance between controlling inflation and managing subsidy burdens.
Simultaneously, rising fuel prices create a ripple effect throughout multiple industries, including agriculture and manufacturing. The high logistics costs exert pressure on exports as well as on micro, small, and medium enterprises (MSMEs).
In such a situation, a major price shock can severely reduce growth momentum, turning into a situation of near-stagnation.
Policy Priorities
The current situation requires us to implement proactive policy measures. We need to expedite the diversification of energy sources by leveraging renewables, alternative fuels, and enhancing efficiency to reduce our structural dependence on imported oil. It is crucial to reconsider our strategic reserves, which should involve international cooperation and flexible access strategies. Financial tools such as hedging frameworks can help stabilize the exposure of vulnerable sectors, particularly micro, small, and medium enterprises (MSMEs). Simultaneously, diplomatic efforts are crucial. Energy markets are closely linked with geopolitics, and efforts to de-escalate tensions are crucial for restoring stability.
Conclusion
Will an oil price shock result in the downfall of the global economy? No. Nevertheless, it will test its resilience. The global economy today is better equipped than in the past, yet it is also more interconnected and susceptible in several ways. The threat does not stem from a collapse, but from prolonged stagnation marked by inflation, slow growth, and rising inequality. Therefore, the crucial question is not if the shock will happen, but whether policymakers are prepared to tackle its consequences.
The author is Senior Fellow, Pahle India Foundation, specializing in policy analysis and international trade.