As the weakening rupee pushes inflationary pressures due to rising crude oil import prices, should RBI raise interest rates?
Time can never mend, the careless whispers of …
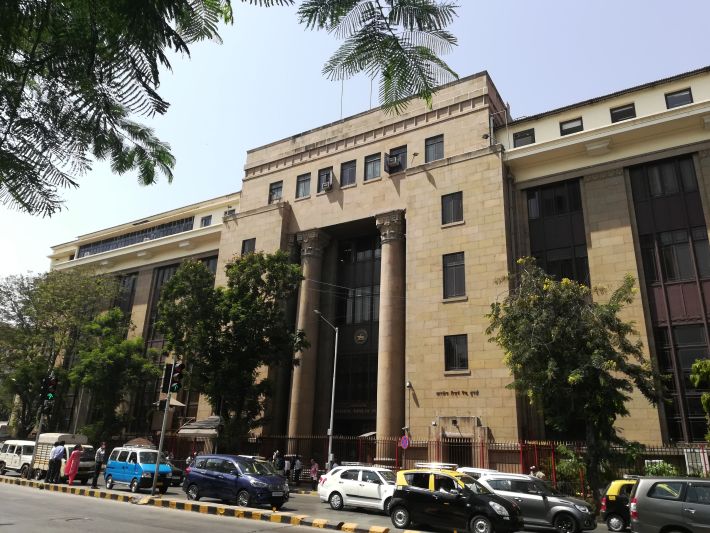
As the RBI marches ahead, for the upcoming monetary policy meeting this June, whispers from the corridors echo around several policy options to defend the rupee – by deploying forex reserves, raising interest rates, or perhaps announcing another foreign currency non-repatriable (FCNR) deposit scheme. The whispers in policy corridors are plentiful, but which policy option will help RBI to tide over the Impossible Trinity, remains a moot question.
The rupee has been weakening and is under stress for several reasons. The Hormuz crisis has put a leash on global energy supplies and pushed up crude oil prices. They had crossed the $110 per barrel mark, and peaked at $116.73 per barrel in May 2026. [It has now come down to $95.69.] This imposed a heavy strain on India which imports 88% of its crude oil requirements. This energy shock amplified the pressure, as the current account was already under stress due to tariffs and sanctions imposed by the US. In 2025, this had hurt our export competitiveness. Textiles, gems and jewellery, as well as engineering goods, bore the brunt of these very high tariffs and India lost competitive advantage. More recently, even our information technology (IT), and information technology enabled services (ITeS) have also started coming under pressure due to the rise of artificial intelligence (AI) and large language models (LLMs), which effectively act to replace largely manual and repetitive work, a lot of which is outsourced to India.
Meanwhile, the lack of substantial listed AI plays, high price-to-earning (P/E) ratios, overvaluation (as compared to other Asian markets), and a rapidly depreciating INR currency pushed foreign institutional and portfolio investors (FIIs and FPIs) to scamper to the exits from the Indian equity market, withdrawing more than $52 billion to date. Cumulative returns of negative 14% in US $ terms is going to become a high bar for them to come back and invest again in Indian markets. Meanwhile, better returns, increasing commodity prices, and lack of other perceived and acceptable investment options, also saw a discernible shift of investments to gold and silver, which increased gold imports putting further strain on the rupee. Hence, unlike earlier times, the capital account could not offset the current account deficit.
The persistent lowering of interest rates by RBI, ostensibly to stimulate GDP growth, also narrowed the differential between US and Indian interest rates. This also resulted in the playing out of the Mundell-Flemming script, and lowering attractiveness of rupee denominated assets. As RBI prepares to announce the June policy, it has to navigate under the constraints imposed by the "impossible trinity'. As the weakening rupee pushes inflationary pressures due to rising crude oil import prices, should RBI raise interest rates?
This is a difficult and uncomfortable option. There is a hope that higher interest rates will address the demand side to control inflation and attract capital flows back, and put a floor to further deterioration of the currency. Similar outcomes can also be expected from an FCNR deposit scheme, but, the deeper fear is that it will tighten liquidity and stymie growth. This uncomfortable trade-off puts RBI in the trilemma of the impossible trinity. Instead of relying solely on monetary policy solutions, the government can also pitch in by incentivising the debt and other asset class markets with tax breaks, to make them attractive and wean the investors away from precious metal hoarding like gold, and silver.
Earlier, policymakers nudged domestic savings towards real estate through tax breaks. The resulting flow of household savings deepened property market. The investors’ behaviour has historically been shaped by the government, by offering public provident fund (PPF), unit-linked insurance plans (ULIPs), pension products, and equity linked saving schemes. The newer tax framework, however, reduced and/or did away with such tax incentives. At the time when gold imports are putting pressure on the rupee, policymakers may revisit, whether well-designed tax incentives in any other format can channel household savings back in productive assets and capital markets.
It’s high time also that we recognise that RBI alone, through monetary policy, cannot do all the heavy lifting. We may find comfort in searching for simple policy prescriptions, but problems are deep-rooted and structural. Such unidimensional choices will carry economic pain and distress, as well as, make the constraints of the trilemma harder to resolve.
Dr Sarika Rachuri is an economist who teaches at ICFAI Business School Mumbai. Dr. Badri Narayanan Gopalakrishnan is an Distinguished Fellow, Pahle India Foundation and former head, trade, NITI Aayog.