Govt, pvt sector must collaborate to bring women and migrants in formal banking

The global study on financial and digital inclusion appreciates the DBT and JAM initiatives by the Indian government

GN Bureau | December 16, 2016

#Brookings   #financial inclusion   #banking   #DBT   #JAM   #India  


India ranks in the middle of a group of 26 emerging economies regarding access to formal financial services, according to a global study. The Brookings Financial and Digital Inclusion Project (FDIP) 2016 report has given India – with 860 million adult population – an overall score of 71 percent. In ‘country commitment’ India scores 100 percent, 72 percent in ‘mobile capacity’ and 94 percent in ‘regulatory environment’ and 44 percent in ‘adoption’.

Kenya tops the list, scoring 84 percent – five percentage points higher than Colombia which scores second, with 79 percent. The first annual FDIP report was published in 2015, where it studied the state of financial inclusion across 21 countries. The findings of 2016 report, which added Dominican Republic, Egypt, El Salvador, Haiti, and Vietnam in its sample, show continuing progress across the global financial inclusion landscape. 

“This assessment is driven in part by the recent launch of comprehensive financial inclusion strategies in several countries and, more broadly, by substantial progress in enhancing the digital financial services ecosystem,” the report said.

Last year India scored 72 percent. Kenya topped the list in 2015 too. The biggest improvement, however, in scores between the two years was made by Philippines, which increased its overall score by eight percentage points. The increase was driven in part by the launch of its national financial inclusion strategy, as well as its strong performance in terms of mobile capacity.

Uganda was the lowest income economy among the countries ranked at the top of the FDIP scorecard.  “Uganda’s high score was driven in part by its strong levels of mobile money adoption (the second-highest among the FDIP countries as of 2014) and the amendment of the 2004 Financial Institutions Act,” the report says. Among other provisions, the amendment provides a legal basis for the regulation of agent banking and empowers the central bank to establish more than one credit reference bureau, the report adds.
 
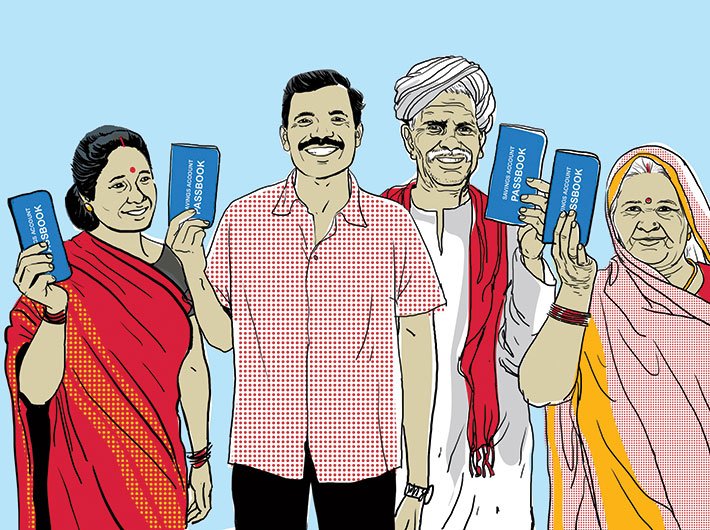
The report appreciates the DBT and JAM initiatives by the Indian government.  “Digital mechanisms are key components of India’s financial inclusion drive,” the report says. For example, the report states, the PMJDY program seeks to channel all government benefits to beneficiaries’ accounts and promote its Direct Benefits Transfer (DBT) scheme.  “The program explicitly notes a desire to reach out to youth and to leverage nontraditional mechanisms, such as mobile devices and telecommunications companies’ cash-out-points. In this vein, the Jan Dhan Yojana, Aadhaar and Mobile numbers initiative (also known as the “JAM trinity”) was developed to combine biometric identification initiatives with mobile access to financial services in order to directly transfer subsidies to beneficiaries and consequently advance efficiency and reduce leakages,” the report adds.

The report highlights a few challenges cum opportunities in furthering financial inclusion in India. A key challenge is the lack of awareness of the formal banking and financial services among customers. “The government and private sector stakeholders must work together to address barriers to financial inclusion among women, 67 migrants, and other underserved populations,” the report says. Ensuring that risk-based KYC requirements are implemented effectively is one necessary step to reducing barriers surrounding financial access and usage, the report notes.

“Additionally, accelerating interoperability of electronic wallets could advance usage of these services by promoting convenience for customers,” the report concludes.


Comments


Other News

MDR on UPI: Can sustainability come without weakening the network?

The extraordinary transaction volumes and value (₹29.82 Lakh crore in August 2026 alone) of the Unified Payments Interface (UPI) have made it not only an Indian success story, but a global one. In 2024, UPI accounted for nearly 49% of the world’s real-time payment transaction volume, with more th

The Xi-Trump summit: The unending rivalry

Diplomacy is akin to an art, wherein the summitry, conflict resolution and negotiations form apt constituents of the entire context of deal making and “playing for keeps” in the international arena. The Xi-Trump summit in Washington last week, in which the American president broke all conside

“Indians, yet treated like outsiders”

Moving to Delhi-NCR for education can be an exciting experience for students from Northeast India. It gives us a chance to meet new people, experience a different culture and become more independent. But living away from home also comes with challenges that people who have not experienced them may not al

Import duty on major edible oils cut

The government has reduced the Basic Customs Duty (BCD) on major imported crude edible oils with a view to moderating domestic edible oil prices, providing relief to consumers and mitigating inflationary pressures arising from the sharp increase in international edible oil prices.  

From pyramid to platform: BRICS agenda for Global South

In his opening address at the 18th BRICS Summit in New Delhi on September 12, prime minister Narendra Modi did something India`s diplomacy has been building towards for three years: he moved the ‘Voice of the Global South’ from a slogan to a work plan. Addressing the leaders, he argued that t

How to realise the full transformative potential of PM-JAY

The Pradhan Mantri Jan Arogya Yojana (PM-JAY), a welfare scheme which covers approximately 45 crore beneficiaries across India, provides cashless health cover of Rs. 5 lakh per family per year. It is the largest health insurance scheme which helped crores of poor families by reducing out-of-pocket expend
Upcoming Conferences


-->

Archives

Current Issue

Opinion

Facebook Twitter Google Plus Linkedin Subscribe Newsletter

Twitter