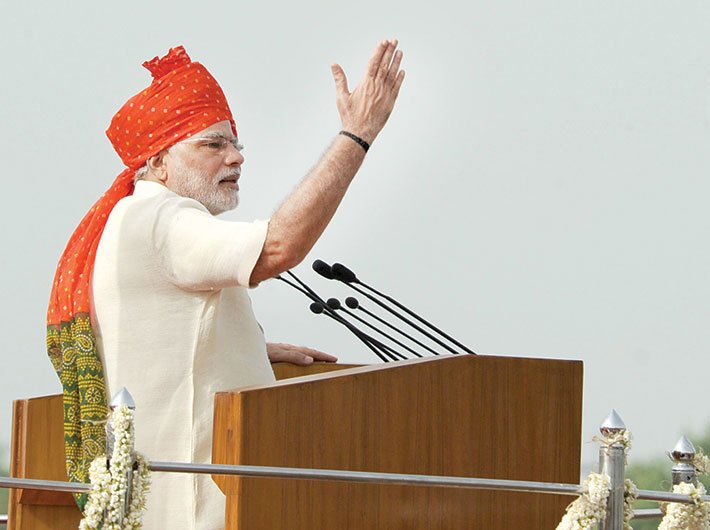
One year into office, prime minister Narendra Modi is still in a mission mode – to launch new or revamped government schemes. Even as he launched three new schemes on May 9, one of his first, the pradhan mantri jan dhan yojana (PMJDY), remains the flagship scheme – its success hinged to the success of the NDA government.
From his speech at the Madison Square Garden in the US to election rallies to his statements on social media, the scheme, touted as a game changer, has been top on Modi’s mind, but has it changed anything in its first eight months?
The scheme envisages universal access to banking facilities with at least one basic banking account for every household, along with financial literacy and access to reasonable credit, to be complemented by insurance and pension. The beneficiaries get a RuPay debit card having an inbuilt accident cover of '1 lakh and after six months an overdraft facility of '5,000, provided the account is ‘active’ during the period. Those who opened their first bank accounts between August 15, 2014 and January 26, 2015 also got a life cover of '30,000.
Amid all the cheering, there have been discerning voices of bankers and experts who have raised concerns. Reserve Bank of India (RBI) governor Raghuram Rajan was the first to raise a red flag when he said mere opening of accounts will not help and the real aim should be to keep these accounts operational or else it will lead to large amount of dormant accounts.
The concerns raised by Rajan almost came to be true. On revising the target (from the earlier 7.5 crore to 10 crore by January 26, 2015) in November, finance minister Arun Jaitley admitted the problem and said efforts should be made to raise the deposit level in the zero balance accounts through financial literacy programmes. He asked the mission to take up financial literacy.
Even as questions were raised on the viability of the scheme, PMJDY on January 20 entered the Guinness Book of World Records for opening the maximum number of bank accounts in the shortest possible time. The number of zero balance accounts came down from 71 percent in the first week of January to 57.9 percent on March 31, after the launch of direct benefit transfer (DBT).
Three more social security schemes have now been launched as extensions to the PMJDY. The pradhan mantri suraksha bima yojana (PMSBY) and pradhan mantri jeevan jyoti bima yojana (PMJJBY) would provide insurance cover in the event of death or disability due to an accident. The third, the Atal pension yojana (APY), would address old-age income security needs.
The real success of the PMJDY will, however, depend on how many people are accessing institutional credit or how effective the insurance cover will be as a social security net. As of now figures are far from impressive, rather they are dismal. According to the department of financial services, the total number of accidental insurance claims received is 174, out of which 79 have been settled. Further, 158 claims under life insurance were received by the department, out of which 93 have been settled. The insurance benefit has shown almost no results, as the scheme has several riders.
Similarly, whether the RuPay card leads to a cashless economy will be yet another denominator in assessing the success of the scheme. Jaitley had said the '5,000 overdraft facility could be used as an instrument of microfinance. In spite of clarifications by the government, bankers say, it is still unclear who can avail this benefit.
Another pain point is the communication infrastructure of banks, with most yet to be fully computerised. Then there is the issue of manpower crunch and lack of training of banking staff to cater to this particular segment that had never been to a bank.
Eight months may be too short a period to gauge the full impact of the PMJDY, but is enough to indicate the need for a review.