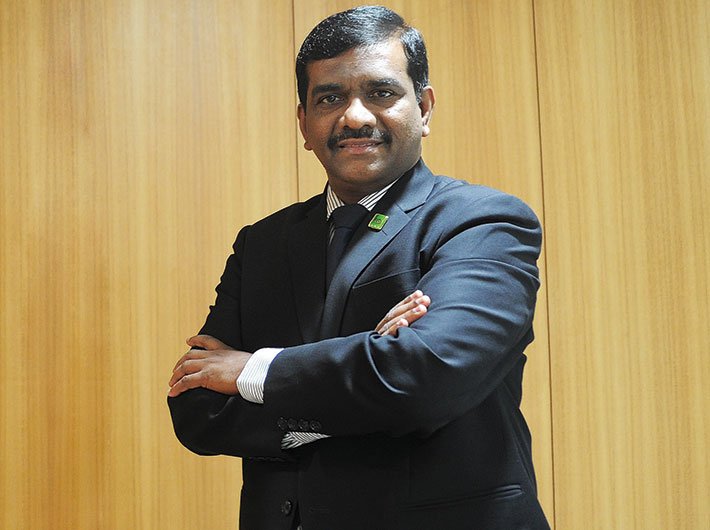
With OBC’s standalone profit of Rs 21.62 crore, OBC executive director Rajkiran Rai G speaks about challenges and hurdles before the banking sector and ways to tide over them
Oriental Bank of Commerce (OBC) has a reason to smile at a time when many of the public sector banks (PSB) are struggling due to bad loans, non-performing assets (NPA) and economic slowdown. While the combined net loss of 20 PSBs stood at Rs 16,272.34 crore for the fourth quarter, OBC reported standalone profit of Rs 21.62 crore. OBC executive director Rajkiran Rai G spoke to Sweta Ranjan about the challenges and hurdles before the banking sector and the ways to tide over them.
The banking sector is facing a gigantic problem of NPAs and bad loans. Your bank too nearly doubled provisions for gross NPAs. What are the factors behind the sudden surge in NPAs?
We had a similar problem in 1991 too when the NPA in banking industry had reached very high levels. But over a period of time, with capitalisation from the government, banks solved all this and we came out very strong. So, whenever there is economic downturn, these things do happen. Another thing you need to understand is that today we lack long-term funding institutions in the Indian banking sector. Earlier, there were institutions which were meant for long-term infrastructure financing; now these institutions are far and few. Commercial banks which are not really meant for long-term infrastructure funding have occupied this space. The economic downturn severely affected our banks. When investments started picking up, the Indian economy was looking great. We never thought that there will be such a downturn in the economy. There are two or three factors, like proper policy and legal interventions, because of environmental issues that affected us. We were all hoping that the economy will bounce back, things will change and the units will do well and the investments will continue. When we saw that the things were not turning around, and Reserve Bank came in – a slight nudge from them by way of asset quality review (AQR) was basically to recognise these problems and resolve these issues. Now we are in the next phase, the resolution phase. That is how the spurt in NPAs happened.
Why is the NPA a bigger problem for public sector banks?
If you see across the world, generally commercial banks are highly regulated. Our prudential norms are very tight. Infrastructure loans are generally 15-20-year loans. We go with certain assumptions, but 15-20 years is too long a period for any assumption to stand. For example, if I project certain cash flows, then there will be lot of policy changes in between. There will be a lot of changes in the economy, so my predictions may go wrong. Corrective mechanism is not built into this kind of funding, basically because we are commercial banks, not long-term lenders. We are into nation-building. We have a few of the best airports in the whole world today. This would not have been possible but for the bank funding. We have the best road infrastructure today. All these things are possible because of bank funding. Assumptions have gone wrong today and things are bad, but the private sector is not a big player in these sectors. It’s only the nationalised banks that fund particularly these kinds of projects which are very long term. Today the NPAs are more in the infrastructure sectors like steel, power, road and textiles. So naturally, since our exposure is more, our NPAs also will be more. If you look at private sector banks which are highly profitable today, they are more into retail. You can’t do the retail loan and think of the nation’s growth. The nation’s growth needs infrastructure growth and in the downturn definitely affects. We need to have some patience to resolve these issues.
What policy support do you expect from the government in easing NPA woes?
We need support both from our regulator and also the government. From the government side, what we are looking at is legal framework. The Bankruptcy Code Act is already enacted, so we are looking forward for some more strengthening of the DRT (debts recovery tribunal) structure. So a quick recovery mechanism is what we are looking at. Through a strong legal framework, we will be able to recover NPAs very quickly. From the regulator side, we need some support particularly in handling accounts which are stressed but where we feel that they can become viable with some forbearance from the regulator. This will help us to pass through this difficult phase.
Pradhan Mantri Jan-Dhan Yojana [PMJDY] is one of the dream projects of the NDA government. How has been your bank’s performance?
Under PMJDY, we have opened more than 36 lakh accounts. It is one of the very good performances. Today in these accounts, we have nearly Rs 3,000 crore balance. More than 47 percent of PMJDY accounts are linked to Aadhaar today. The DBT (direct benefits transfer) is the next big thing which has already started happening. It is reaching the beneficiary account directly. With Aadhaar linkages, which the prime minister is pushing very strongly, we have covered half of our PMJDY accounts and we expect it to be around 70 percent complete by December. I think DBT will substantially help in saving and filtering accounts which are fraudulent in nature and benami accounts. Today, we release the money and within a few hours, it is credited in the beneficiary’s account, which is the beauty of DBT. We are looking at improving the living standards of those beneficiaries who are at the bottom of the pyramid.
The government has been talking of capital infusion in PSU banks. Has this been done?
We got capital in March and we expect that some more capital will come during this year also. In a way, today we are adequately capitalised, but with the anticipated credit growth we may need some more capital.
At the same time, the government also talks of reducing its stake in ownership of the PSU banks. Do you see any contradiction between capital infusion and reduction of stake?
It’s a thought process basically from the major stakeholder, that is, the government, that they want to gradually dilute their stake. If you ask me whether it’s the right time or not, I would say time is not ripe because we are all going through a corrective stage today. A corrective mechanism is on. Maybe it will take another five to six quarters before banks really stabilise and when some serious NPA resolutions will happen, we will be back to good profits. Then the government can think of diluting their stake, because I think at this point of time the government may not be able to really dilute their stake at a reasonable price.
Loan disbursals under the MUDRA scheme has come under scanner as it is believed that the benefits are yet to reach the last-mile borrower. What are the loopholes?
It has reached the last-mile borrower because last year we have done a disbursement of Rs 1,308 crore under the MUDRA [Micro Units Development and Refinance Agency] scheme. This year the target is Rs 1,800 crore. Whether every person who is eligible has been touched? The answer is ‘no’ because it is not possible. Here we have a limited infrastructure. We have not created any fresh infrastructure for PMJDY or MUDRA or other things. We are using our existing infrastructure of bank networks and BCs [banking correspondents] to reach them. It takes time because we are not building any fresh infrastructure in a big way. We are only strengthening the existing infrastructure.
[email protected]
(The interview appears in the June 16-30, 2016 issue of Governance Now)