Ahead of budget, the mid-year report says economy is in a classic Keynesian slump, and calls for the Keynesian solution: a rise in government investment, funded by rising fiscal deficits. Will Jaitley oblige?
In which country does December mark the middle of the year? That is when the mid-term report of our finance ministry was published. The economic survey, which is presented to parliament the day before the budget, gives the macroeconomic context in which the budget has been framed; if anyone wanted more frequent reviews, he could turn to the Reserve Bank. Now, so many trivial speeches of deputy governors have to be accommodated in the bulletin of the Reserve Bank that the space for analysis has shrunk. The finance ministry has taken to reviewing the economy between budgets. I would have thought that if the budget was to be presented at the end of February, the time for a mid-year review would be August or September. But last year, the finance minister presented a budget in July. He had no economic advisor then, and the absence showed: no economic survey accompanied the budget. The only point of the budget was patronage – replacement of sundry beneficiaries of the Congress by those of the Bharatiya Janata Party.
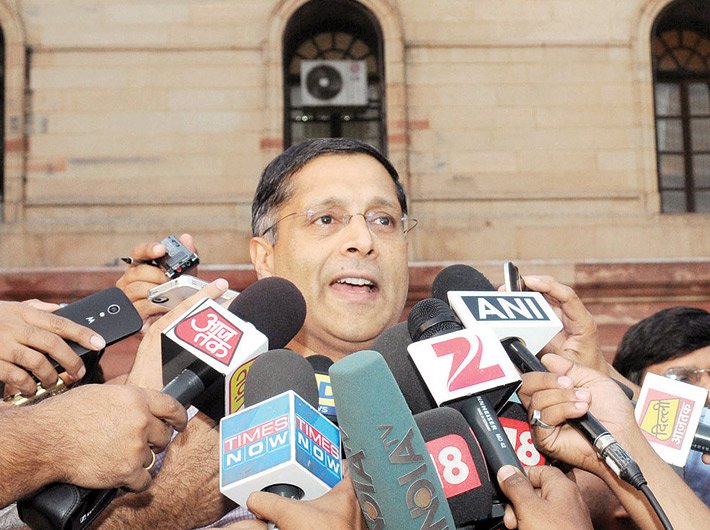
The mid-term report this year had the touch of Arvind Subramanian, the new economic advisor. It began with figures of a Macroeconomic Viability Index for the Fragile Five. It was the sum of three undesirables – inflation, current account deficit and fiscal deficit – for the fragile five – Brazil, India, Indonesia, South Africa and Turkey. Between 2009 and 2014, the MVI for India fell by about a quarter, while it rose for the other four. As a result, India no longer had the highest MVI: Turkey had beaten it. That is not a great achievement, but modest good luck.
Then the report gives a figure showing the time series of real policy rate from 2004 till 2015, from which it draws the conclusion that inflation in India exceeded inflation in comparator countries. It may have, but the figure does not show that. As far as I can see, it shows that the Reserve Bank kept its policy rate low, and let it fall below inflation from 2008 till 2012. Reserve Bank’s interest rates are largely irrelevant. It is banks’ lending rates that matter; and they were above inflation most of the time, though it may be possible to argue that they were still too low.
The report gives a series of rise in rural wages between 2007 and 2014 and holds it partially responsible for inflation. This does not follow. The rural labour market is extremely competitive: there are many labourers for every employer, and they never combine into trade unions. The rise in rural wages was truly remarkable; but it suggests shortage of rural labour. Those years saw the highest economic growth rates in India’s recorded history; the growth led to shortages, especially in unskilled labour markets. The causation is from growth to wage growth, not from wage growth to inflation.
But inflation has come down, and one reason is the fall in international prices of mineral oil products. The report points out another reason: that the Rupee appreciated almost 10 per cent in the year after August 2013. It could do so only because Reserve Bank was not adding to its foreign exchange reserves. There was a time when it used to do so with great gusto. It should have bought dollars after mid-2013 because the economy was slowing down; additions to reserves would have increased domestic money supply and stimulated the economy. It is surprising that the governor of Reserve Bank failed to do so.
Then it comes to the correct, Keynesian explanation of the economic slowdown: that the UPA era saw a massive investment boom which collapsed and landed us in the doldrums of the NDA era. This is a coincidence in my view: the UPA did nothing to deserve the good times, nor did the NDA to deserve the bad times. But that is how the economic god distributes his favours. Here, the mid-term report gives two figures with the same title: growth rate of fixed capital formation. Actually, only the first figure – 1.10 – is correctly titled; the next figure gives investment-income ratios. The pairing of the two figures is misleading, because the growth rate is quarterly and runs up to September 2014 whereas the investment ratios are annual and run up to March 2013. Both the figures should have been quarterly and have run up to the same date.
The report draws the conclusion from these disparate figures that India suffered from its own version of the “balance sheet syndrome”. This is an interesting import: the term has been missing in Indian debates. What it means is that in the west various governments – think of Greece – borrowed too much from the market and then could not repay their debt; that led to prolonged crises. In India, it was private companies that borrowed too much. Part of the reason was that the government had invited private investment into infrastructure, and got the private companies to borrow from the financial institutions under its ownership.
After all those stumbles, the report comes to the correct conclusion: that the Indian slump is a classic Keynesian slump. It calls for the Keynesian solution: a rise in government investment, funded by rising fiscal deficits. That would have appealed to Manmohan Singh, whose governments spent as if there was no tomorrow. Will Jaitley be equally, cheerfully myopic? We will soon find out.
(The article appeared in February 16-28, 2015, issue)